
Knowing how to calculate your HMRC mileage claim correctly is the difference between getting every penny you are owed and leaving money on the table — and for 2026/27 the sums have changed. The car and van rate rose from 45p to 55p per mile on 6 April 2026. This HMRC mileage calculator guide walks you through the new approved rates, shows worked examples at 5,000, 10,000 and 15,000 miles, explains exactly how much tax relief you can claim back, and helps you decide whether to use form P87 or Self Assessment.
HMRC Approved Mileage Rates for 2026/27
HMRC’s Approved Mileage Allowance Payment (AMAP) rates for 2026/27 are:
| Vehicle type | First 10,000 miles | Above 10,000 miles |
|---|---|---|
| Cars and vans | 55p per mile | 25p per mile |
| Motorcycles | 24p per mile (flat) | 24p per mile (flat) |
| Bicycles | 20p per mile (flat) | 20p per mile (flat) |
The car and van rate for the first 10,000 miles increased from 45p to 55p, announced on 21 May 2026 and backdated to 6 April 2026. Every other rate is unchanged: 25p above 10,000 miles, 24p for motorcycles and 20p for bicycles. The current figures are published by HMRC in Travel — mileage and fuel rates and allowances.
If you are calculating a claim for 2025/26 or an earlier year, use 45p rather than 55p for the first 10,000 miles — that was the approved rate from 2011 until 5 April 2026.
The tax year runs 6 April 2026 to 5 April 2027. Your 10,000-mile threshold resets on 6 April each year. The same rates apply to petrol, diesel, hybrid and electric vehicles — there is no separate EV mileage rate under AMAP.
If you carry a colleague on a business journey, you can claim an additional 5p per passenger per mile on top of the standard rate.
For a deeper breakdown of how the 55p rate works and what it covers, see our 55p per mile HMRC explained guide.
Step-by-Step HMRC Mileage Calculation
Follow these three steps to calculate your total mileage allowance for the tax year:
Step 1 — Total your business miles. Add every qualifying business journey from 6 April to 5 April. Ordinary commuting (home to a permanent workplace) does not count.
Step 2 — Split at the 10,000-mile threshold.
- Miles 1 to 10,000: multiply by 55p
- Miles 10,001 onwards: multiply by 25p
Step 3 — Add both amounts together. The combined figure is your total mileage allowance — the amount you can claim or be reimbursed tax-free.

Worked Examples at Different Mileage Levels
Example 1: 5,000 Business Miles
You drive 5,000 business miles in 2026/27. Every mile falls within the 55p band.
- 5,000 x 55p = £2,750
Your total mileage allowance is £2,750.
Example 2: 10,000 Business Miles
You drive exactly 10,000 business miles. The entire mileage falls within the higher rate.
- 10,000 x 55p = £5,500
Your total mileage allowance is £5,500. The 25p rate only applies from mile 10,001.
Example 3: 15,000 Business Miles
You drive 15,000 business miles, crossing the threshold partway through the year.
- 10,000 x 55p = £5,500
- 5,000 x 25p = £1,250
- Total: £6,750
Once you pass the 10,000-mile mark, every additional mile is worth 25p rather than 55p. If you reach 10,000 miles in December, all journeys from January to April use the 25p rate. Note that the gap between the two bands is now much wider — 30p per mile rather than 20p — so tracking exactly when you cross 10,000 miles matters more than it used to.
How Much Tax Relief Can You Claim Back?
If your employer reimburses you at the full AMAP rate, no further claim is needed. But if your employer pays less than 55p/25p per mile — or nothing at all — you can claim Mileage Allowance Relief (MAR) on the shortfall. The actual cash refund depends on your income tax rate. Since the rate rose in May 2026, this now includes the many employers still reimbursing at the old 45p.
Employer Shortfall Calculator
Suppose you drive 10,000 business miles and your employer reimburses you at 20p per mile:
- HMRC approved amount: 10,000 x 55p = £5,500
- Employer reimbursement: 10,000 x 20p = £2,000
- Shortfall (tax-deductible amount): £3,500
Your tax relief is then calculated on that £3,500 shortfall:
| Tax band | Rate | Tax relief amount |
|---|---|---|
| Basic rate (20%) | £3,500 x 20% | £700 refund |
| Higher rate (40%) | £3,500 x 40% | £1,400 refund |
| Additional rate (45%) | £3,500 x 45% | £1,575 refund |
If your employer pays nothing at all, the full AMAP amount becomes your deductible shortfall, and the refund is even larger.
Note that a £3,500 shortfall exceeds the £2,500 P87 limit, so this driver would need to claim through Self Assessment rather than a P87 — a threshold that more employees now cross because of the higher rate.

Tax Relief Examples With Zero Employer Reimbursement
| Annual business miles | AMAP allowance | Basic rate refund (20%) | Higher rate refund (40%) |
|---|---|---|---|
| 5,000 | £2,750 | £550 | £1,100 |
| 10,000 | £5,500 | £1,100 | £2,200 |
| 15,000 | £6,750 | £1,350 | £2,700 |
These figures show just how significant unclaimed mileage relief can be. A higher-rate taxpayer driving 15,000 unreimbursed business miles is owed £2,700 per year from HMRC — £400 more than the same driver was owed under the 45p rate.
When to Use Form P87 vs Self Assessment
The route for claiming your mileage relief depends on your employment status and the size of your claim.
Use form P87 if:
- You are an employee (not self-employed)
- Your total employment expense claim is £2,500 or less for the year
- You do not already file a Self Assessment return
Form P87 can be submitted online through your HMRC personal tax account or by post. HMRC typically processes claims within 6 to 12 weeks and will either adjust your tax code or send a direct refund. For the full walkthrough, see our P87 form online guide.
Use Self Assessment if:
- Your total employment expense claim exceeds £2,500
- You are self-employed or a sole trader
- You already file a Self Assessment return for other reasons (rental income, high earner, etc.)
Sole traders enter their mileage as a vehicle expense under simplified expenses, which reduces taxable profit and therefore your income tax and Class 4 NIC liability. For the self-employed method, see our sole trader mileage claim guide.
You can backdate mileage claims by up to four years, so if you have not claimed for previous tax years, you may be owed a substantial refund. Remember to use the rate that applied in each year: 55p for 2026/27 onwards, and 45p for 2025/26 and earlier.
Common Calculation Mistakes to Avoid
Applying 25p from mile one. The 25p rate only kicks in after 10,000 miles. Using 25p throughout means a driver doing 10,000 miles claims £2,500 instead of the correct £5,500 — a £3,000 shortfall.
Still using 45p for 2026/27. The rate rose to 55p on 6 April 2026. A driver who applies the old 45p rate to 10,000 miles claims £4,500 instead of £5,500, underclaiming by £1,000 — worth £200 in lost relief at the basic rate and £400 at the higher rate.
Using calendar year instead of tax year. The 10,000-mile threshold runs from 6 April to 5 April. Resetting your count on 1 January will distort your calculation.
Forgetting the rate change mid-year. If you hit 10,000 miles in November, every business journey from December to April uses 25p. Continuing at 55p overstates your claim and risks an HMRC enquiry.
Including commuting miles. Travel between home and a permanent workplace is ordinary commuting, not business mileage. Including it inflates your claim and could trigger penalties.
Reconstructing mileage from memory. HMRC expects a contemporaneous log — recorded at the time of travel, not estimated at year end. Without proper records, your entire claim can be rejected. A GPS-based mileage tracker solves this problem entirely.

Automate Your HMRC Mileage Calculation With Tripbook
Calculating your mileage claim manually means tracking every journey, monitoring the 10,000-mile threshold, totalling everything at year end, and working out the tax relief. One missed journey or miscounted mile reduces your refund.
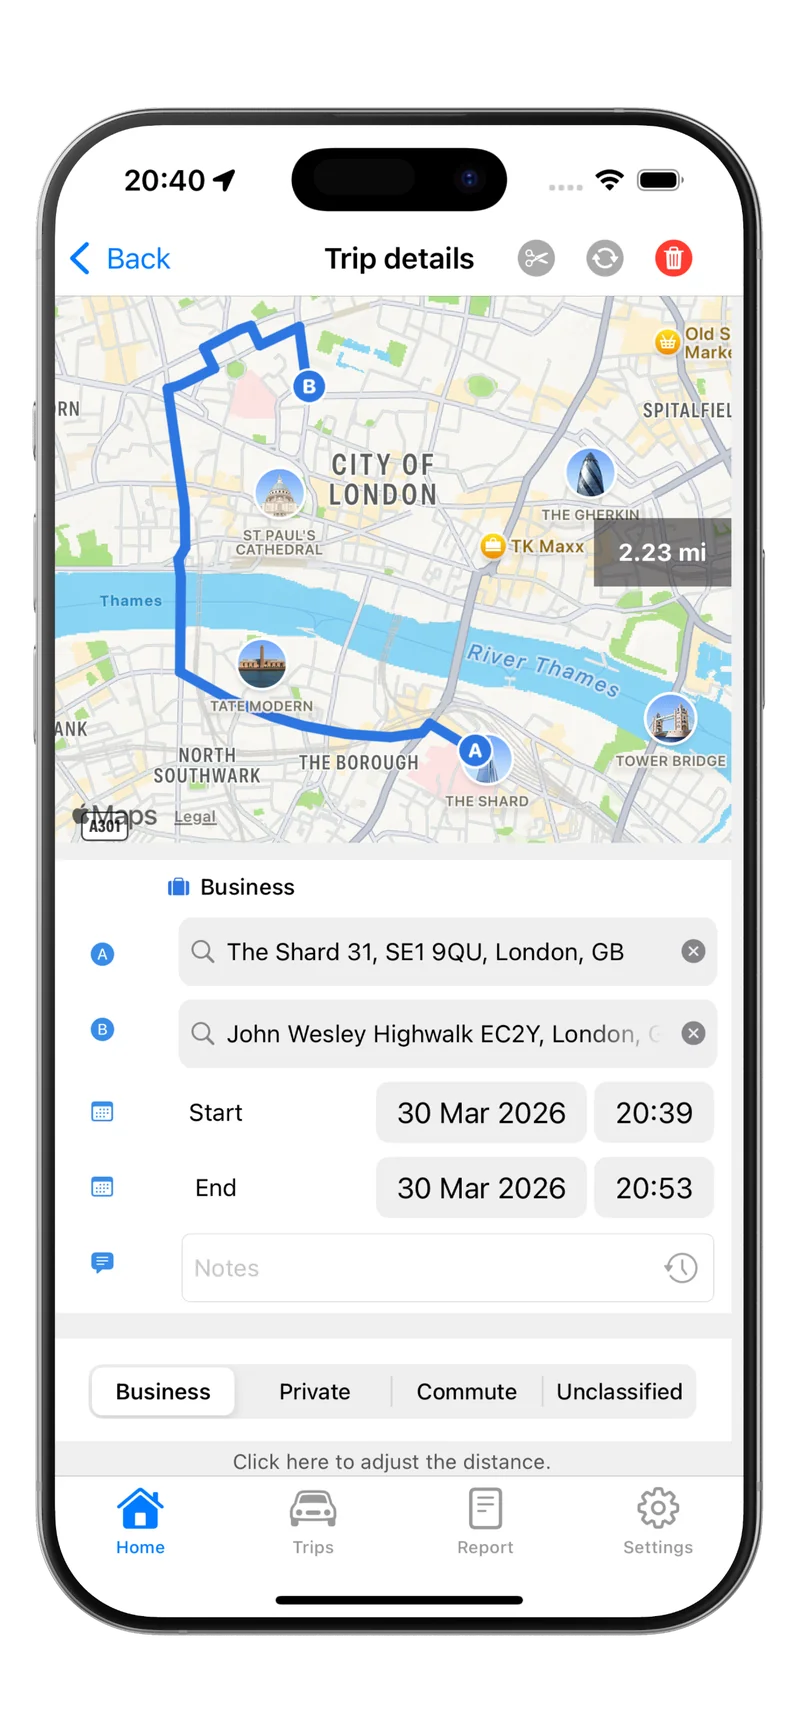
Tripbook automates the entire process. The app logs every business journey via GPS, tracks your cumulative mileage in real time, alerts you when you approach the 10,000-mile threshold, and generates an HMRC-ready mileage report at year end. Whether you claim via P87 or Self Assessment, Tripbook gives you the accurate records HMRC requires.
Download Tripbook from the App Store and start tracking your mileage today.