
If you use your personal vehicle for work, the IRS gives you two ways to deduct those costs: the standard mileage rate and the actual expenses method. Choosing the right one can mean hundreds or even thousands of extra dollars back at tax time.
This guide breaks down both methods with real numbers, shows you when each one wins, and explains the rules you need to follow.
How the standard mileage rate works
The standard mileage rate is the simpler option. You multiply your business miles by the IRS rate and deduct the result. The current business rate is 76 cents per mile, effective July 1, 2026.
2026 is a split year. The IRS raised the rate mid-year, so miles driven January 1 through June 30, 2026 are deducted at 72.5 cents, and miles driven July 1 through December 31, 2026 at 76 cents (IRS standard mileage rates). If you are still filing for the 2025 tax year, that rate was 70 cents per mile.
That single rate is meant to cover gas, insurance, depreciation, maintenance, and general wear and tear. You do not need to track individual expenses. You only need an accurate, date-stamped record of your business miles — the date now decides which rate applies.
Example: You drive 12,000 business miles from July onward. Your deduction is 12,000 x $0.76 = $9,120. Had you driven the same 12,000 miles in the first half of the year, it would be 12,000 x $0.725 = $8,700.
On top of the standard rate, you can still deduct parking fees and tolls related to business trips. Those are separate line items.

How the actual expenses method works
With the actual expenses method, you add up every cost of owning and operating your vehicle for the year. Then you multiply that total by the percentage of miles that were business-related.
Deductible expenses include:
- Gas and oil (wondering if you can just deduct fuel? See can you write off gas for work)
- Insurance premiums
- Repairs and maintenance
- Tires
- Registration and license fees
- Lease payments (if applicable)
- Depreciation (if you own the vehicle)
Example: Your total vehicle costs for the year are $14,000. You drove 18,000 total miles, and 10,800 of those were for business (60%). Your deduction is $14,000 x 0.60 = $8,400.
The catch is clear: you need receipts for everything, and you still need a mileage log to calculate your business-use percentage. For a refresher on what the IRS expects from your log, check our guide on IRS mileage log requirements.
Key rules and restrictions
Before you pick a method, know these IRS rules:
First-year lock-in. If you want to use the standard mileage rate for a vehicle, you must choose it in the first year the car is available for business use. If you start with actual expenses, you are locked out of the standard rate for that vehicle permanently.
Switching directions. You can switch from the standard mileage rate to actual expenses in a later year. But you cannot go the other direction. Once you claim actual expenses, the standard rate is off the table for that car.
Fleet and depreciation limits. You cannot use the standard mileage rate if you operate five or more vehicles at the same time, or if you have claimed accelerated depreciation (like Section 179) on the vehicle.
Leased vehicles. If you lease, whichever method you choose in the first year must be used for the entire lease period.
Not sure which method wins? Calculate both in your first year and compare. You can always switch from the standard rate to actual expenses later, but not the other way around. Starting with the standard rate keeps your options open.
When the standard mileage rate wins
The standard rate tends to be the better deal when:
- You drive a fuel-efficient or low-cost vehicle. A paid-off Honda Civic costs far less to operate than 76 cents per mile, so the standard rate gives you a larger deduction than your real costs.
- You drive a lot of business miles. The more miles you log, the bigger your deduction. A rideshare driver putting in 25,000 business miles at the current rate would get a $19,000 deduction regardless of actual costs.
- The rate went up this year. July’s increase from 72.5 to 76 cents widened the standard rate’s advantage. Every mile driven in the second half of 2026 is worth 3.5 cents more than the same mile in January, while your real running costs did not jump on July 1.
- You want simplicity. No shoebox of gas receipts. No spreadsheet of insurance payments. Just accurate mileage records and a quick multiplication.
When actual expenses win
Actual expenses tend to beat the standard rate when:
- You drive an expensive vehicle. A new truck or luxury SUV with high insurance, fuel, and depreciation costs may run to more than 76 cents for every mile you put on it, which is the bar the flat rate now sets.
- Your business-use percentage is high. If 90% of your driving is for business, you get to deduct 90% of a large cost base.
- You have significant depreciation. A vehicle purchased new for $50,000 generates meaningful depreciation deductions in the first few years.
A side-by-side example
Let’s say you drive 15,000 business miles out of 20,000 total miles (75% business use).
| Standard Mileage Rate | Actual Expenses | |
|---|---|---|
| Business miles | 15,000 | 15,000 |
| IRS rate | $0.76/mi | — |
| Total vehicle costs | — | $16,000 |
| Business % | — | 75% |
| Deduction | $11,400 | $12,000 |
In this scenario, actual expenses save you $600 more. But if your total vehicle costs were only $12,000 instead of $16,000, the standard rate would win comfortably ($11,400 vs $9,000).
The lesson: run the numbers for your situation.
The break-even point moved in July
The rate increase did not just make the standard method pay more. It moved the line at which the two methods trade places, and it moved it against actual expenses.
The comparison reduces to one number. Your actual-expenses deduction is your total vehicle costs multiplied by your business-use percentage, and that percentage is business miles divided by total miles. Work the algebra through and the business miles cancel out entirely. What is left is simple:
Actual expenses only beat the standard rate when your all-in vehicle cost per mile driven — every mile, business and personal — is higher than the standard rate itself.
That threshold used to be 70 cents in 2025, then 72.5 cents in the first half of 2026. Since July 1 it is 76 cents. Your car has to be 8.6% more expensive to run than it did last year before actual expenses come out ahead.
In the example above, $16,000 of costs across 20,000 total miles works out to 80 cents per mile. That clears the 76-cent bar, so actual expenses win — but only just, by $600 rather than the $1,500 those same numbers would have delivered at the old 70-cent rate. Cut the costs to $12,000 and you are at 60 cents per mile, well under the bar, and the standard rate wins by $2,400.
This is why the higher rate is worth re-running your comparison over. Vehicles that narrowly justified the receipt-keeping burden of actual expenses at 70 cents may no longer justify it at 76. If you calculated once a few years ago and have kept the same method out of habit, the answer may have changed underneath you — especially if your car is now older, mostly depreciated, and cheaper to run than it was when you first ran the math.

Both methods require mileage tracking
Here is something many drivers overlook: even if you choose the actual expenses method, you still need a mileage log. The IRS requires you to know your total miles and your business miles to calculate the business-use percentage.
And if you choose the standard rate, your mileage log is the entire basis of your deduction. No log means no deduction if you are audited.
Your log needs to include the date, destination, business purpose, and miles driven for every trip. For a breakdown of exactly what to record, see our complete mileage tracking guide.
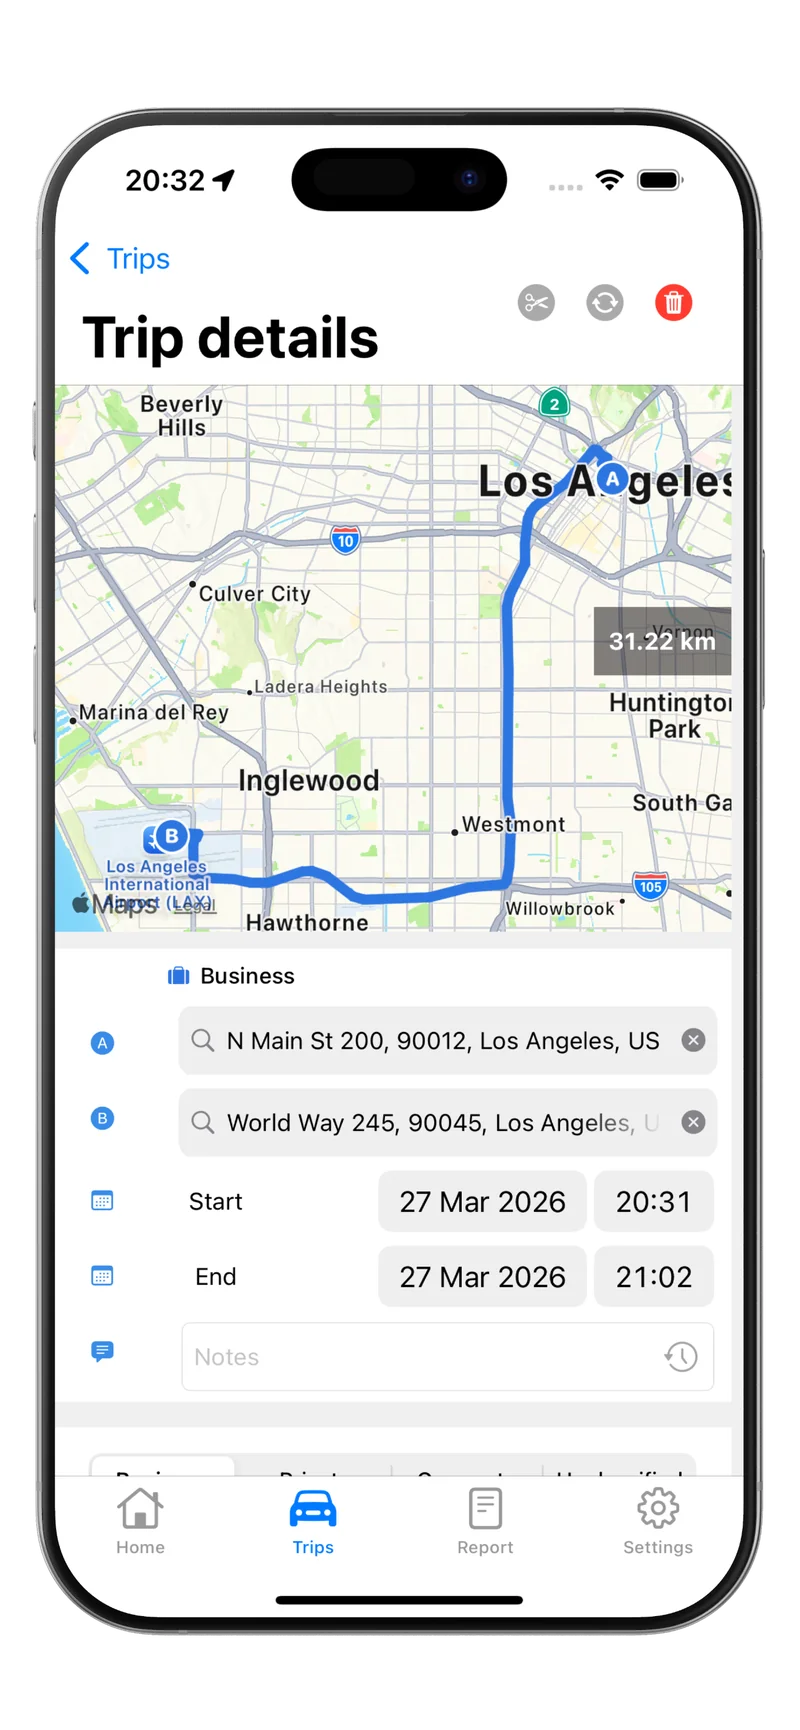
Tripbook automatically records every drive using GPS, so you never have to remember to start a tracker or write anything down. At tax time, export your full log as a PDF, CSV, or XLS file ready for your accountant.
How to decide: a quick checklist
- Calculate both. Add up your actual vehicle costs for the year, then divide by your total miles. If the result is under 76 cents, the standard rate wins and you can stop there. For the standard-rate figure itself, remember to split 2026: pre-July miles at 72.5 cents, July onward at 76 cents.
- Consider your vehicle. Older, cheaper cars usually favor the standard rate. Newer, expensive vehicles often favor actual expenses.
- Think about effort. The standard rate requires only a mileage log. Actual expenses demand receipts for every cost category.
- Check your eligibility. Make sure you haven’t already claimed accelerated depreciation or started with actual expenses on this vehicle.
- Plan for the future. If you are unsure, start with the standard rate in year one. You can always switch to actual expenses later.
What about the reimbursement side?
If you are an employee receiving mileage reimbursement from your employer, the method your company uses affects your paycheck. Most employers reimburse at or near the IRS standard rate. Learn more about how reimbursement works in our mileage reimbursement for employees guide and estimate your totals with our mileage reimbursement calculator.
Start tracking your miles today
Whichever method you choose, accurate mileage records are the foundation. Without them, you risk losing deductions, failing an audit, or leaving money on the table.
Tripbook makes it effortless. The app runs in the background on your iPhone, automatically logging every trip with GPS precision. Classify trips with a swipe and export IRS-compliant reports whenever you need them.
Download Tripbook free on the App Store and start building the mileage log that protects your deductions.